
Banks handle millions of tasks every day. They open accounts, check IDs, move money, review loans, and answer questions. For many years, people did much of this work by hand, and it was slow. Today, intelligent automation banking is changing that story. It combines software robots, artificial intelligence (AI), and smart data tools so that routine work gets done faster and with fewer mistakes.
In 2026, customers expect quick help at any hour. They want to open an account on a phone, get a loan answer in minutes, and feel safe while doing it. Banks also face tighter rules, rising costs, and clever fraud attempts. Smart automation helps with all of these problems at the same time.
This guide explains the topic in plain words. You will learn what the technology is, how it works, where banks use it, and what risks to watch. You will also find tables, a simple roadmap, and answers to common questions. Whether you are a student, a bank worker, or a team leader, this article will give you clear and practical knowledge.
What Is Intelligent Automation
Think of a busy bank branch. A worker checks forms, types data into a computer, and sends emails. Much of that work follows the same steps every time. Now imagine a digital helper that does those steps for you, learns from past cases, and asks a person only when something looks unusual. That is the basic idea.
In simple terms, intelligent automation banking means using software robots and AI together to handle bank tasks. Robots follow rules. AI adds the ability to read, learn, and make good guesses. When the two work as a team, they can handle jobs that were once too messy for a machine, such as reading a scanned document or understanding a customer’s message.
It is different from old-style automation. Old tools only worked when data was neat and the steps never changed. Smart tools can deal with surprises. They can read handwriting, spot odd patterns, and improve over time. Humans stay in charge. The technology takes over the boring, repeated work, so people can focus on advice, care, and hard decisions.
The Main Technologies Behind It
Several tools work together to make this possible. Knowing each one helps you see the full picture.
Robotic process automation (RPA). These are software “bots” that copy what a human does on a screen. They click, copy, paste, and fill in forms. They never get tired and rarely make typing errors.
Artificial intelligence and machine learning. Machine learning studies past data to find patterns. A bank can use it to guess which payments look risky or which customers may need help.
Natural language processing (NLP). This lets computers understand human words. It powers chatbots and tools that read emails or contracts.
Optical character recognition (OCR). This turns pictures of text, such as a scanned passport, into words a computer can use.
Process mining and workflow tools. These show where work gets stuck, so banks know what to fix first.
Generative AI. Newer tools can draft summaries, write replies, and explain complex rules in simple language. Banks use them with care, and a human usually reviews the result.
Together, these tools form a “digital workforce” that supports human staff.
Why Banks Are Moving Fast in 2026
Many forces push banks toward smart automation. The first is customer demand. People are used to fast apps from shopping and ride services. They expect the same speed from a bank. A loan that takes ten days feels too slow now.
The second force is cost. Running branches, call centers, and back offices is expensive. Automation can lower the cost of each task, which lets a bank offer better prices and still stay healthy.
The third force is competition. Online banks and financial technology (fintech) firms were built with modern tools from day one. Older banks must keep up or risk losing customers.
The fourth force is risk and rules. Banks must follow strict laws on money laundering, privacy, and fair lending. Checking everything by hand is hard and can lead to missed problems. Automated checks run all day and leave a clear record.
The fifth force is staff happiness. Many workers do not enjoy copying numbers from one screen to another. When bots handle this, people can do work that is more interesting and more helpful. Banks that offer such jobs also find it easier to keep good employees.
Real Uses in Daily Banking
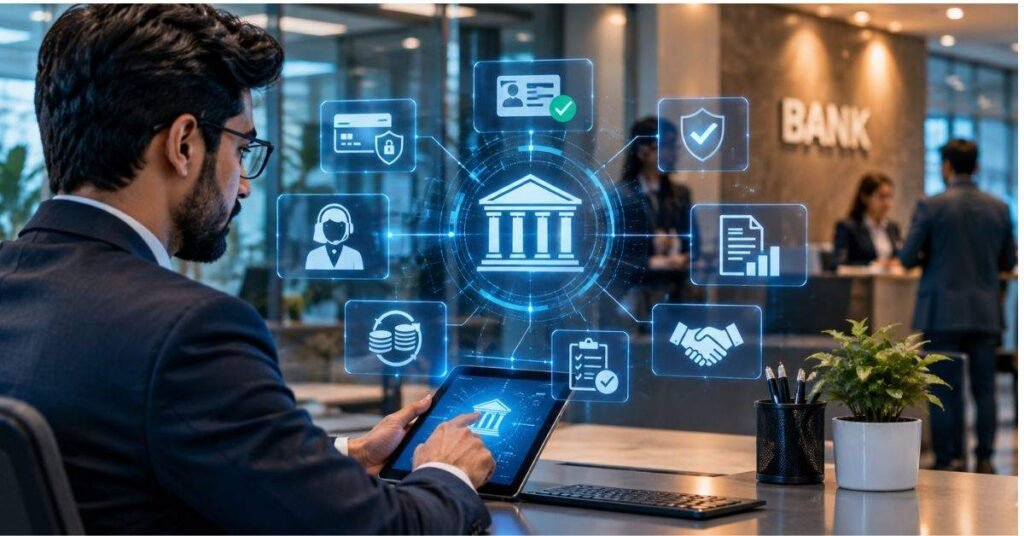
Smart automation already supports many parts of a bank. Here are some of the most common examples.
Opening accounts. Customers upload an ID and a selfie. The system reads the document, matches the face, checks the details, and finishes setup in minutes.
Loan processing. Tools collect pay slips and statements, read them, and score the risk. A human officer then reviews special cases.
Fraud detection. AI watches card and transfer activity in real time. If a payment looks strange, such as a large purchase in a faraway country, the system can pause it and alert the customer.
Customer service. Chatbots answer simple questions, such as “What is my balance?” or “How do I block my card?” Hard questions go to a human agent with the full chat history attached.
Compliance and reporting. Bots collect data, fill out reports, and flag suspicious activity for review. This supports anti-money-laundering (AML) and “know your customer” (KYC) checks.
Payments and reconciliation. Software matches thousands of transactions against records and highlights the ones that do not fit.
Claims and disputes. When a customer disputes a charge, automation gathers the proof and speeds up the answer.
Visual Guide: Tables and Charts
Pictures and tables make ideas easier to remember. These two tables show how work changes and how different tools fit different jobs.
Banking Tasks Before and After Smart Automation
| Task | Manual Way | Automated Way |
|---|---|---|
| Account opening | Paper forms, long waits | Digital forms, quick checks |
| Loan review | Days of document handling | Documents read in minutes |
| Fraud alerts | Found after the loss | Flagged in real time |
| Customer questions | Wait in a phone queue | Instant chatbot reply |
| Compliance reports | Built by hand each month | Built by bots, ready on demand |
Which Tool Fits Which Job?
| Tool | Best For | Simple Example |
|---|---|---|
| RPA bots | Repeated, rule-based steps | Moving data between systems |
| Machine learning | Finding patterns | Spotting unusual card use |
| NLP | Understanding words | Reading customer emails |
| OCR | Reading scanned files | Extracting data from an ID |
| Generative AI | Drafting and summarizing | Writing a case summary for review |
Simple chart idea: the automation journey
Step 1: Fix one small task → Step 2: Add AI to handle messy data → Step 3: Link many tasks end to end → Step 4: Improve with data and feedback.
Benefits for Banks and Customers
The advantages reach almost everyone involved. Let us start with the bank. When intelligent automation banking handles repeated tasks, work moves faster and costs go down. Error rates fall because machines follow the same steps each time. Staff gain time for tasks that need judgment and kindness.
Customers see the difference quickly. Accounts open sooner. Loan answers arrive faster. Help is available at night and on weekends. Fraud warnings come before money disappears, which gives people peace of mind.
Risk teams also benefit. Automated systems keep a clear trail of what was done and when. That makes audits easier and helps leaders prove they followed the rules.
Here are the main gains in short form:
- Speed: Tasks that took days can finish in minutes.
- Accuracy: Fewer typing and copying mistakes.
- Savings: Lower cost per transaction.
- Better service: Quick, steady support at all hours.
- Stronger safety: Faster fraud and risk checks.
- Growth: Banks can serve more customers without hiring at the same rate.
These benefits matter most when banks pick the right tasks first and measure results with care.
Risks and Challenges
Smart tools are powerful, but they are not magic. Leaders should know the problems before they begin.
Poor data. AI learns from data. If the data is old, messy, or unfair, the results will be weak. Cleaning data is often the hardest part of intelligent automation banking.
Old systems. Many banks still run core software that is decades old. Connecting new tools to old systems takes time and skill.
Bias and fairness. If an AI model learns from unfair past decisions, it may repeat them. Banks must test models often to make sure they treat people equally.
Cyber threats. More connected tools can mean more doors for attackers. Strong security is a must.
Staff worries. Some workers fear losing their jobs. Honest talk, training, and new roles help build trust.
Over-trust in machines. AI can be wrong. Banks need humans to review key decisions, especially in lending and fraud cases.
Hidden costs. Projects can grow larger than planned if goals are unclear.
The good news is that each risk has a fix. Careful planning, regular testing, and clear human oversight keep the technology safe and useful.
Rules, Security, and Trust
Banks hold people’s money and private facts, so trust is everything. Any smart system must follow the law and protect customers.
Rules differ by country, but common themes appear everywhere. Banks must protect personal data, explain automated decisions when asked, and treat customers fairly. In the United States, groups such as the Consumer Financial Protection Bureau and FinCEN set expectations for fair treatment and for fighting financial crime. For AI safety, many firms use the NIST AI Risk Management Framework as a guide. Other regions, including the European Union, have their own AI and data rules, so global banks must check each place where they work.
Good practice includes a few simple habits:
- Keep a human in the loop for important choices.
- Write down how each bot or model works, so it can be checked.
- Test models for bias and mistakes on a regular schedule.
- Limit who can see sensitive data, and log every access.
- Prepare a backup plan if a bot fails.
When banks show customers that their data is safe and their treatment is fair, they earn lasting trust. That trust is worth more than any single cost saving.
A Simple Roadmap to Get Started
A bank does not need to change everything at once. A clear, step-by-step plan works best. Here is a path that many teams follow for intelligent automation banking projects.
Step 1: Pick a clear goal. Choose a problem that matters, such as slow account opening or high call volume.
Step 2: Map the process. Write down every step of the task. Use process mining tools if you have them, so you see where delays happen.
Step 3: Start small. Run a pilot on one task. Early wins build support and teach the team what works.
Step 4: Check data and security. Make sure data is clean and safe before adding AI.
Step 5: Train people. Teach staff how to work with bots, review results, and handle exceptions.
Step 6: Measure results. Track time saved, errors cut, and customer happiness.
Step 7: Grow with care. Add new tasks one by one, and share lessons across teams.
Many banks also set up a small “center of excellence.” This is a group of experts who set standards, share tools, and help each department. Having this group keeps projects tidy and prevents the same mistakes from repeating.
Trends to Watch After 2026
The field is moving quickly, and several trends are worth watching.
AI agents. Instead of doing one fixed step, agent-style tools can plan a series of steps, such as gathering documents, checking them, and preparing a draft decision. Banks will keep humans in charge of final approval.
Generative AI helpers. Staff will use them to summarize long files, draft emails, and answer policy questions faster.
Personal banking advice. Apps will give more tailored tips, such as warning you about a bill or suggesting a way to save.
Real-time everything. Faster payment systems push banks to check risk and finish tasks in seconds.
Stronger AI rules. Governments continue to write clearer rules for AI. Banks that build good habits now will adjust more easily.
Cloud and open banking. Cloud tools make it easier to add new features, and open banking lets customers share data safely with trusted apps.
Focus on skills. Banks will invest more in training so that workers can team up with technology rather than compete with it.
Banks that stay curious, test new ideas carefully, and keep people at the center will be best prepared.
Frequently Asked Questions
What is intelligent automation in simple words
It is the use of software robots and AI to do repeated tasks quickly and learn from data. People stay in charge of important choices.
Will automation replace bank workers
It will change many jobs, but people are still needed for advice, care, and hard decisions. Many roles shift toward checking results and helping customers.
Is automated banking safe
Yes, when banks use strong security, test their systems, and follow privacy rules. Customers should still use strong passwords and watch for scams.
How can a small bank begin with intelligent automation banking
Pick one slow, repeated task, run a small pilot, and measure the results. Then grow step by step.
What is the difference between RPA and AI
RPA follows fixed rules to copy human clicks. AI can learn from data and handle messy or new situations.
Conclusion
Banking is changing, and smart technology is at the center of that change. When banks use software robots, AI, and clear human oversight together, they can work faster, make fewer mistakes, and serve customers better. Customers get quick answers and safer accounts. Staff get more time for meaningful work. Leaders gain clearer records and stronger control.
The main lesson is simple: start small, protect data, keep people involved, and measure what matters. Intelligent automation banking is not about replacing human care. It is about removing slow, boring work so that people can do what they do best.